


I’ve been using the OCBC Premier Dividend+ Account to grow my spare cash for some years. It used to offer a fantastic 3.7% interest rate, which rivaled Singapore Government Securities such as T-bills without the hassle of rolling and locking in for a 6-month period.
But good things don’t last forever. In May 2024, OCBC dropped the Premier Dividend+ Account interest rate to 3.3% for the highest tier. And the bank is slashing the interest rate again now.
Let’s look at the details.
I just received an email from OCBC stating that starting from 1 February 2025, the interest rate for the Premier Dividend+ Savings Account will be revised to up to 2.95%.
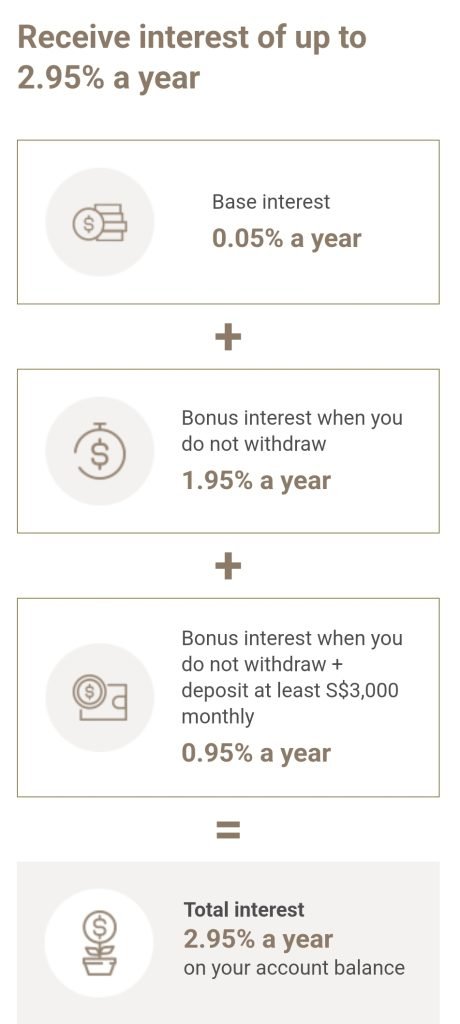
The interest is based on 3 tiers
- Base interest – 0.05% per year
- Bonus interest when you do not withdraw – 1.95% per year
- Bonus interest when you do not withdraw + deposit at least S$3,000 monthly – 0.95% per year
It adds up to 2.95% as below if you fulfill all the critera:
So what is next? Here is how I look at it.
SGD Interest Rate Continues to Decline Despite Revised Fed Rate Projection
We all know that Donald Trump’s sweeping win in the US election had a significant impact on the financial market, including the USD interest rate direction. One consensus is that a Trump presidency will lead to high inflation and prolonged high interest rates.
Despite this, SGD interest continues moving down. I noticed that the SGD interest rates offered by banks continue to decline, affecting everything from fixed deposits, high-interest accounts and mortgage loan interest rate.
A quick check on SingSavers shows the latest fixed deposit rates (as of Jan 2025) as below.
| Bank | Best interest rate (p.a.) | Tenure | Minimum SGD deposit |
| Bank of China | 3.00% (mobile banking placement) 2.90% (over the counter placement) | 3 months | S$500 (mobile banking) S$10,000 (over the counter) |
| CIMB | 2.75% (personal banking) 2.80% (preferred banking) | 3/6 months | S$10,000 |
| Citibank | 3.00% (Citigold Private Client) 2.90% (Citigold) 2.40% (Citi Priority, Citibanking or Citi Plus) | 3 months | S$250,000 (Citigold Private Client/Citigold) S$50,000 to S$3 million (Citi Priority, Citibanking or Citi Plus) |
| DBS / POSB | 2.45% | 12 months | S$1,000 |
| Hong Leong Finance | 2.70% | 7 months | S$50,000 |
| HSBC | 2.65% | 3 months | S$200,000 and above |
| ICBC | 3.00% (e-banking) (≥S$200,000) 3.00% (over the counter) (≥S$200,000) | 3 months | S$500 (e-banking) S$20,000 (over the counter) |
| Maybank | 2.80% 3.15% (Deposit Bundle Promotion) | 6 months | S$20,000 |
| OCBC | 2.25% (branch) 2.45% (online) | 6 months | S$30,000 |
| RHB | 3.00% (Premier Banking) 2.90% (Personal Banking) | 3 months | S$20,000 |
| SBI | 2.65% | 6 months | S$50,000 |
| Sing Investments & Finance LTD (SIF) | 2.70% (mobile banking placement) 2.70% (over the counter placement) | 3 months | S$10,000 |
| Standard Chartered | 2.75% (Priority Private Banking) 2.65% (Priority Banking) 2.55% (Personal Banking) | 6 months | S$25,000 |
| UOB | 2.50% | 6 months | S$10,000 |
Is the OCBC Premier Dividend+ Account’s 2.95% Interest Still Worth It?
Honestly, the 2.95% interest rate is not easy to come by. To qualify, you need to be an OCBC Premier Banking customer with an initial deposit of S$50,000 in fresh funds. But to become an OCBC Premier Banking customer, you must deposit or invest at least S$350,000.
Additionally, to earn the bonus interest, you must not make any withdrawals and must deposit at least an additional S$3,000 monthly.
For most people, it’s still easier to qualify a decent interest rate from T-bill (3.05% interest in the latest auction on January 2, 2025).
But I think this account is still useful if you have the following needs:
- To earn bonus interest for a large sum of money – Many high-interest accounts limit bonus interest to certain balances. For example, UOB One limits the bonus interest for up to the first $150K balance. The bonus interest rate for OCBC Premier Dividend+ has no cap, which means you will earn bonus interest on your entire balance.
- To maintain adequate liquidity and flexibility – If you are preparing a downpayment on a property or making a significant purchase without knowing the exact timing—it is important to have flexible financial options. Unlike fixed deposits or T- bills, you are not bound by a fixed term. Although it is possible to terminate your fixed deposit early or sell your T-bills if necessary, having more adaptable solutions can be advantageous.
However, if you are putting the money for a longer term than 6 month, or you don’t need absolute guaranteed returns, you should consider other investment options potentially lock in a longer term yield.
Let’s not forget that the trend of interest rates is still declining, whether at a fast or slow pace. While the yield today may not be as attractive as it was a few months ago, it will likely be better than the rate in the near future.
Let Me Summarize…
If you are savings SGD for short term up to 6 months, you can go for
- Bonus interest account such as OCBC Premier Dividend+, UOB One etc.
- Money market investment such as Moomoo’s Cash Plus and other Auto Sweep account offered by your stock broker.
- Short Term Treasury Bills
If you have a longer time horizon than 6 months, you should consider investment instruments that can help you lock in the current high yield without taking excessive risks. Because when you roll your fixed deposit or T-bills a few months down the road, you will realise that you can only get a lower yield.
As a licensed investment advisor, I specialize in retirement planning and portfolio management. If you’re interested in exploring alterantive investment options and strategies, apply for a non-obligatory investment discovery meeting through this link.
For more savings and investing tips, join our Telegram Channel or Subscribe to our Retire Rich Weekly Newsletters using the form below.